Inventory a lender can actually lend against
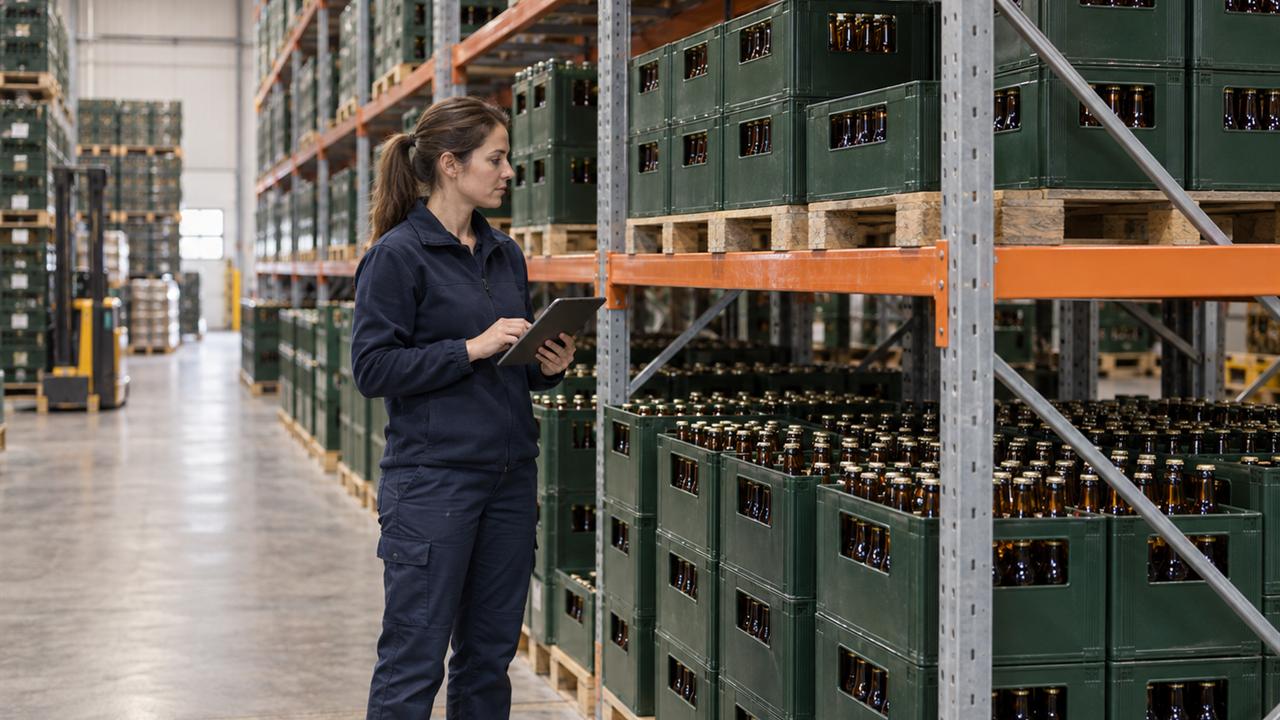
Food stock is worth money and rarely counts as collateral: nobody can tell a lender what is in the warehouse, whose it is, what condition it is in and what it is worth — on a Tuesday, without a site visit.
Why food stock rarely counts as collateral
Food traders and processors carry serious working capital in physical goods, and finance it on terms that assume none of it exists. The gap is not one of value — it is one of verification.
What a lender is up against
- A borrowing base certificate assembled by hand, monthly, from the borrower's own spreadsheet
- A field audit twice a year that is accurate on the day and decays immediately after
- No way to see whether goods were sold, moved, pledged elsewhere or quietly spoiled
- Perishability priced as a blanket haircut, because condition is invisible
- The result: a low advance rate, or no inventory line at all
With Collateral Insights
- A borrowing base that recalculates as stock moves, not once a month
- Independent confirmation from the warehouse operator, not only from the borrower
- Movements, sales and releases visible as they happen, with an audit trail behind each
- Condition data feeding eligibility, so a deteriorating lot leaves the base automatically
- The result: a defensible advance rate, negotiated on evidence
Every inventory facility rests on the same four answers
A lender financing stock needs to know four things, continuously rather than occasionally. Most of the cost of inventory finance comes from the difficulty of answering them — not from the risk itself.
- Does it exist? Quantity confirmed by the party holding it, against the borrower's declaration.
- Whose is it? Title and any competing claim, including goods already sold but not yet shipped.
- Is it still good? Condition and remaining shelf life, which for food is the difference between collateral and disposal cost.
- What is it worth? Valuation against a reference the lender accepts, marked as the market moves.
- Existence
- Confirmed by operator · 09 Sep
- Title
- Unencumbered · no competing claim
- Condition
- In spec · 96 days stored
- Shelf life
- 124 days remaining
- Valuation
- € 412,800 · marked 11 Sep
- Advance rate
- 70 % · € 288,960
Independent confirmation from the warehouse
The structural weakness of inventory finance is that nearly all the information reaching the lender comes from the party with most to gain from it looking good. That is not an accusation but bad control design — and everybody prices it in.
Collateral Insights is built for three parties. The borrower declares, the warehouse operator independently confirms, and the lender sees both plus the difference. Nobody has to trust a number only one party can see.
Where goods sit with a third-party warehouse, that operator's confirmation is the spine of the file — the role a warehouse receipt plays in commodity finance, issued continuously instead of on paper at a point in time.
| Source | Tonnes | As of |
|---|---|---|
| Borrower declaration | 1,240.0 | 08 Sep |
| Operator confirmation | 1,213.5 | 09 Sep |
| Weighbridge outloads | 26.5 | 08 – 09 Sep |
| Reconciled | 0.0 | Explained |
A borrowing base that maintains itself
Eligibility rules as code
Your facility's actual criteria — location, age, condition, concentration limits, ineligibles — applied per lot and re-evaluated on every movement.
Independent confirmation
Warehouse operators confirm holdings through their own access, so the lender's view never depends solely on the borrower's word.
Condition-aware valuation
Shelf life and storage history feed eligibility directly, so a lot that is deteriorating drops out of the base before it becomes a write-off.
Covenant and threshold alerts
Advance rate, concentration and headroom monitored continuously, with breaches raised to both sides at once rather than discovered at the next certificate.
Certificates on demand
A borrowing base certificate generated from the live position, with every figure walking back to the record and the party it came from.
- Borrower
- Headroom & what to fix
- Warehouse operator
- Confirm & release
- Lender
- Position, variance & covenants
What it changes
Working capital released
Stock that was financed as if it did not exist starts carrying its share, on an advance rate argued from evidence rather than from caution.
Monitoring cost down on both sides
Fewer manual certificates, shorter field audits, and far less time spent assembling numbers that the system already holds.
Surprises become signals
A deteriorating lot or an unexplained variance surfaces while it is still a conversation, not after it has become a loss.
Start with your current borrowing base
Take last month's certificate and we will show you which lines could have been verified continuously, and what that would have done to your advance rate.